

BEN LEVY, ESG Analyst
Why ‘G’ remains the most reliable engine of long-term value
Ask investors what “ESG” means to them, and the conversation drifts quickly to carbon footprints, supply chains, diversity targets – the environmental (E) and the social (S). Ask them what actually moves the needle on returns, and the answer changes. In a 2024 survey of 47 major institutional investors and asset owners by Stanford Graduate School of Business1, 68% named governance as the primary consideration shaping their ESG-related decisions. Environmental factors trailed at 23%, and Social factors barely registered at 2%.
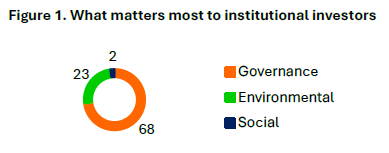
Source: Stanford GSB.
We have spent decades at AVI making this argument through where we allocate capital and how we vote: the businesses worth owning for the long run are, almost without exception, well-governed ones. This is the case for why governance (G) has never stopped being the driver, even as the spotlight moved elsewhere.
The Evidence: Governance as the Value Driver
Governance is arguably the most quantifiable of the three ESG pillars. Where E and S cases can often rest on longer-term or harder-to-isolate outcomes such as decarbonisation across a global supply chain, G is the one where the evidence has had the most time to accumulate. This link between governance and value has been tested repeatedly, and the data continues to confirm it.
MSCI research shows that in the U.S., companies that displayed governance leadership consistently outperformed governance laggards between 2015 and 2023, with an excess annualized return of 2.7% over the full nine-year study (26.3% cumulative)2. That is nearly a decade of compounding evidence that boards which hold management accountable, separate oversight from execution, and protect minority shareholders appear to run better businesses.
The mechanism behind this is straightforward. MSCI’s study of 4,319 global issuers from 2015-2024 found that companies in the top ESG-rating quintile financed themselves at an average cost of capital of 6.8%, against 7.9% for the bottom quintile – a full percentage point, and statistically significant at the 99% confidence level3. Markets, in other words, already appear to price governance quality into the cost of every pound a company raises. Good governance is not a nice-to-have sitting alongside the balance sheet; it is baked into it.
This is echoed at the institutional level. The OECD’s 2025 Corporate Governance Factbook finds 76% of the 52 jurisdictions it tracks now require or encourage the separation of CEO and board chair roles, up from just 44% a decade earlier4. Regulators, like markets, have concluded that governance architecture is not incidental to performance; it is a precondition for it. It is the same logic that has underpinned AVI’s engagement for decades: find where governance lags value and close the gap.
Governance Reform is Not a Straight Line
Progress on governance reform is never uniform. Some jurisdictions push ahead with real conviction, others quietly retreat, and the overall picture looks less like a steady march forward than a patchwork of gains in one market offset by losses in another. Japan is the clearest recent case of the former. Since the Corporate Governance Code was introduced over a decade ago, and revised in July 2026, the share of Prime-listed companies with at least one-third independent directors has risen from 6.4% in 2014 to 98.8% in 20255. Cross-shareholdings have plummeted from 50% of total market capitalization in 1990 to just 11% today6. Progress, but not completion: cross-shareholding unwind remains slower than the headline figures suggest, and disclosure of what companies do with the proceeds is still inconsistent.
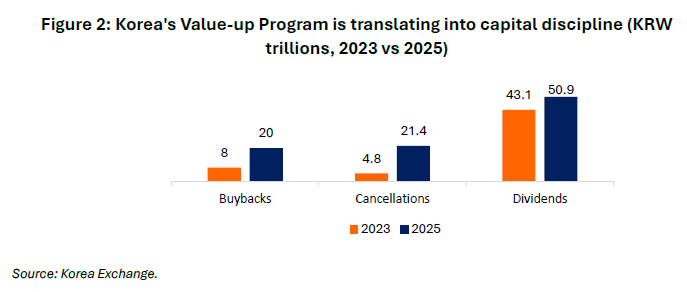
Korea offers an even sharper before-and-after. In the decade before the Corporate Value-Up Program launched in 2024, the KOSPI grew just 35%, against 179% for the S&P 500 and 155% for the Nikkei 2257. In response to persistent demands from foreign and domestic investors to address the issue, the government-initiated actions to improve capital efficiency and align the market closer with global corporate governance best practices. Since the programme began, buybacks have risen from KRW 8.2 trillion (2023) to KRW 20.1 trillion (2025), and cancellations have quadrupled to KRW 21.4 trillion8. The Korea Value-up Index rose 89.4% in 2025 alone, outpacing the broader KOSPI by nearly 14 percentage points.
Set this against the picture in more “mature” markets, and the straight-line narrative breaks down entirely. The UK is home to some of the world’s oldest governance codes, yet lost 88 companies to delisting in 2024, the highest since the financial crisis, against just 18 new listings, despite efforts by the UK government, regulators and the LSE to boost the City’s attractiveness by reforming market rules9. This doesn’t reflect a governance failure, but rather two structural headwinds that have swamped the UK’s governance advantage: nearly a decade of Brexit-related uncertainty that cut London’s share of European IPO proceeds from 40% to 30%10, and a near-total retreat by UK pension funds from domestic equities, whose ownership of the UK stock market has fallen from 39% in 2000 to just 4% in 202311. Good governance did not cause this exodus, and cannot reverse it alone; which is why hands-on engagement matters more in a market like this, not less.
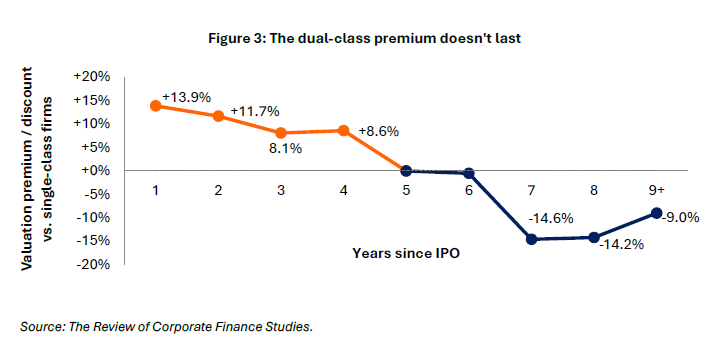
Perhaps the starkest evidence of reform’s non-linearity comes from dual-class shares. Dual-class structures show why markets eventually catch up with governance risk, even when it takes years. A 2024 study spanning 40 years of IPO’s found that dual-class firms trade at a 13.9% valuation premium in their first year on the market (Figure 3), but that premium fully reverses into a discount within seven to nine years, as the gap between insider voting power and cash-flow rights becomes impossible to ignore12.
None of this should surprise a serious observer of corporate governance. Reform is never granted; it is negotiated, market by market, board by board, and it can just as easily be legislated away as it was legislated in. That is precisely why active, informed engagement matters more, not less, in markets where the direction of travel looks settled.
Why Engagement, Not Exit
Governance can regress even in well-regulated markets. The real question is what an investor does about it. A conventional response is to exit – sell out of the underperformer, reinvest where governance is stronger, and leave the valuation gap for the next owner to solve. That does not close a governance discount; it simply changes whose problem it is. We would rather be the ones who close it, and increasingly, the evidence backs that approach.
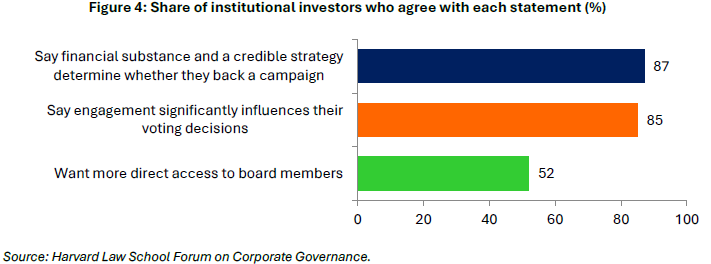
Institutional investors overwhelmingly say engagement shapes outcomes: 85% report that engagement significantly influences their voting decisions, and 52% say they are demanding more direct access to board members than they were a few years ago13. But support must be earned, not demanded; 87% of respondents say they back proposed change at a company only when the financial case is sound and the plan is credible – not because the request was persistent.
Former AVI investee company Hipgnosis Songs Fund is a clear example of what this looks like in practice. Our concerns about the fund’s financial controls, transparency, and the effectiveness of its board had built for some time but came to a head in 2023 when management proposed selling some of their music catalogues to a related party at a steep discount to its carrying value. Rather than sell out, we published a public letter urging shareholders to vote against the proposals, and shareholders responded decisively – 83% voted against continuation, and 84% rejected the sale. Two directors resigned before the AGM and the chairman lost his own re-election vote. We then worked with other shareholders to install two new independent directors, one of whom became Chairman. Within months, a competitive process delivered a bid from Blackstone at a 48% premium to the undisturbed share price14.
Aker is another AVI example that illustrates something related but different: what concentrated ownership can achieve, and where its limits lie. We held a position in the Norwegian industrial holding company from 2008 to 2025, drawn by the alignment of interest with a controlling shareholder that consistently thinks in decades rather than quarters – and has sagaciously allocated capital to the benefit of all shareholders. That kind of patient capital allocation is exactly what we look for in a controlling shareholder, and it has delivered strong returns over the holding period. But it is not a guarantee against misjudgement: Aker Horizons has faced a far harder road than the market expected when it launched in 2020, a point its own Chairman has acknowledged directly15. We take that as validation rather than contradiction of our approach – even well-run, long-term-minded companies benefit from shareholders who keep asking questions, because governance is a standard that has to be maintained, not a box that gets ticked once.
This distinction matters more than it might first appear, as a literal reading of governance scorecards would flag much of our own portfolio at AVI as a problem. Holding companies, by design, concentrate control in a single family or founding shareholder; and thus we likely carry a higher proportion of dual-class structures than the broader market. On a rigid checklist that prioritises board independence and one-share-one-vote, these companies would score poorly. We do not see that as a contradiction of our own argument, we see it as a persistent governance misdiagnosis in the market.
Concentration of control is not, on its own, a governance risk; the absence of accountability is. Telling the two apart, identifying which controlling shareholders behave like Aker’s and which behave like Hipgnosis’s former board, is a skillset that has built at AVI through case-by-case engagement. It also has an evidence base of its own: Credit Suisse’s Family 1000 research finds that family- and founder-controlled businesses have outperformed the broader global universe of non-family-owned companies at an annual average of 404 basis points since 200616.
The broader trend points the same way. 2025 was a third consecutive record year for global shareholder campaigns pushing for change17, with capital-allocation demands now appearing in 31% of them, up from a 19% five-year average – and European AGM seasons are seeing rising opposition to remuneration and share-issuance resolutions, up from 30.7% to 37.9% year-on-year on pay alone18. Engagement, in short, is not a relic of stewardship codes, it is becoming the market’s default response to governance that falls short.
What Good Looks Like Going Forward
If the last decade has taught us anything, it’s that governance progress is measurable, and worth measuring precisely because it can stall or reverse. A few markers are worth watching closely.
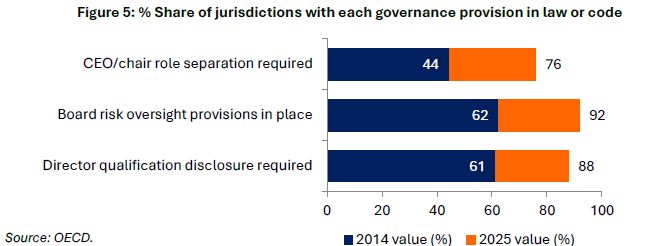
Board independence remains the clearest structural signal, and the shift has been global rather than confined to any single market. Across the 52 jurisdictions the OECD tracks, the share requiring or encouraging separation of the CEO and board chair roles has grown from 44% to 76% since 2014, and board-level responsibility for risk oversight is now written into rules or codes in 92% of jurisdictions, up from 62% a decade ago19. Disclosure has kept pace with structure: 88% of jurisdictions now require or recommend that companies disclose director qualifications, up from just 61% in 2014. What was once a patchwork of local practice has converged into something close to a global norm.
Capital discipline is the second marker. Global dividends hit a record $1.75 trillion in 2024, while buybacks – up nearly 182% since 2012 versus a 54% rise in dividends – have gone from just over half of dividend value to 94% of it20. Set alongside the Korea and Japan figures from earlier in this piece, the pattern is global: boards are being held to a higher standard on what they do with shareholders’ capital, not just how they govern themselves.
The third marker is simpler than it sounds: how a board treats deals that benefit an insider at other shareholders’ expense. Related-party transactions are the clearest test. The OECD finds 94% of the 52 jurisdictions it tracks now require immediate disclosure of these deals, up from 50% in 2016, and 87% require board approval, up from 54% a decade ago. That is a lens we often return to in our own engagement work across the globe.
None of these markers guarantee an outcome. But together, they describe what we look for before we can call a company well-governed: a board that answers to shareholders, capital allocated with discipline, and minorities protected as a matter of structure rather than goodwill.
Closing
Return, for a moment, to the survey we opened with, where 68% of institutional investors named governance as their primary ESG consideration, against 23% for the environment and 2% for social factors21. That gap is not really a verdict on E and S which ask you to price in value that has not yet arrived. G asks something more fundamental, that the people running a business are accountable to the people who own it. There is nothing fashionable about that, it has simply always been correct.
Decades of engagement have taught us that this accountability is never permanently secured. It is built, market by market, board by board, and it must be defended just as deliberately as it was won – in Tokyo and Seoul as much as here in London. That, in the end, is the quiet driver.
Scan to visit our Insights page:
The content of this website is issued by Asset Value Investors Limited (“AVI”), 2 Cavendish Square, London W1G 0PU. AVI is authorised and regulated by the Financial Conduct Authority of the United Kingdom (the “FCA”) and is a registered investment adviser with the Securities and Exchange Commission of the United States. While the Investment Manager is registered with the SEC as an investment adviser, it does not comply with the Advisers Act with regard to its non-U.S. clients.
To the extent that material on this website is issued in the UK, it is issued for the purposes of the Financial Services and Markets Act 2000
Intended Audience
The information on this website is provided to you for informational purposes only and should not be regarded as an offer or solicitation of an offer to buy or sell any investments or related services that may be referenced on this website. The information contained on this website is subject to change without notice.
It is your responsibility to observe all applicable laws and regulations of any relevant jurisdiction.
This website is primarily intended for United Kingdom (“UK”) residents. It is not intended for distribution to, or use by, any U.S. persons or persons in any other country where such distribution, publication or use would be contrary to local law or regulation or in which AVI does not hold any necessary licence or registration. Individuals or entities in respect of whom such prohibitions apply, must not access or use the AVI website.
No Tax or Legal Advice
Nothing on this website constitutes investment, legal, tax or other advice nor should it be relied upon in making an investment decision.
Money Laundering
As a result of money laundering regulations, additional documentation for identification purposes may be required when you make your investment. Full details are contained in the relevant subscription documents.
Investment Decisions
As with all financial or investment matters, you should exercise great care in using the information provided on this website or available through links from this website. You should research the facts, opinions and strategies mentioned in this website before making any financial investment decisions. If you are unsure about the meaning of any information provided, please consult your financial adviser or other professional adviser.
No Warranty; Limitation on Liability
Neither AVI, any of its directors, officers or employees, nor any third party vendor, will be liable or have any responsibility of any kind for any loss or damage that you incur in the event of any failure or interruption of this site, or resulting from the act or omission of any other party involved in making this site or the data contained therein available to you, or from any other cause relating to your access to, inability to access, or use of the site or these materials, whether or not the circumstances giving rise to such cause may have been within the control of AVI, or of any vendor providing software or services support.
All information and content on this website is subject to applicable statutes and regulations, furnished “as is”, without warranty of any kind, express or implied, including but not limited to implied warranties of merchantability, fitness for a particular purpose or non-infringement. We make no warranty as to the operation, functionality or availability of this website, that the website will be error-free or that defects will be corrected.
In no event shall AVI be liable to any indirect, incidental, special or consequential damages arising out of or in connection with the use of this website, the inability to use this site or any products or services obtained or stored in or from this website, whether based on contract, tort, strict liability or otherwise. These limitations also apply to any third-party claims against users.
Intellectual Property
Everything on this website is the valuable intellectual property of Asset Value Investors Limited, or their respective suppliers. We protect our intellectual property rights to the full extent of the law.
Copyright Policy
No permission is granted to copy, distribute, modify, post or frame any text, graphics, video, audio, software code, or user interface design or logos.
Hyperlinks
The existence of hyperlinks should not be construed as an endorsement, approval or verification by AVI of any content available on third party sites. By providing access to other websites, we are not recommending the purchase or sale of products or services provided by the website’s sponsoring organization. We do not review any of these third-party sites. AVI reserves the right to require written consent for, or request the removal of, any links to our website.
AVI disclaims all responsibility and liability for the content on third party sites.
Security
For your protection, we require the use of encryption technologies for certain types of communications conducted through this website. While we provide those technologies and use other reasonable precautions to protect confidential information and provide suitable security, we do not guarantee or warrant that information transmitted through the Internet is secure, or that such transmissions will be free from delay, interruption, interception or error. You acknowledge and agree that users of this website and users, owners, or managers of third party websites may not: (i) collect or store personal data about other users of this website or (ii) upload, e-mail or otherwise transmit any material that contains viruses or any other computer code, files or programs that might interrupt, limit or interfere with the functionality of any computer software, hardware, database or file, or communications equipment that is owned, leased or used by AVI.
Privacy Policy
We encourage you to read AVI’s Privacy Policy which can be obtained by clicking the Privacy Policy button found on the Homepage.
General Terms
Deliberate misuse of any element of this website including, without limitation, hacking, introduction of viruses or similar code, disruption or excessive use or any use in contravention of applicable law, is expressly prohibited and we reserve the right to terminate your access to the website, and at our discretion, pass information to the legal authorities.
We reserve the right at any time on giving notice to change or modify these terms and conditions or to impose new conditions in respect of this website or to change or discontinue any aspect or feature of this website. We shall be entitled to terminate your access to this website at any time on giving notice to you and in any event if you commit any breach of these terms and conditions.
We shall have no liability to you for such termination. Notices may be served by any reasonable method including posting on this website.
You shall indemnify us from and against all actions, claims, proceedings, costs and damages (including any damages or compensation paid by us on the advice of its legal advisors to compromise or settle any claim) and all legal costs or expenses arising out of your use of this website, any breach of any applicable law, statute, ordinance, regulation or third party rights and any breach by you of the software licenses and service agreements governing the software made available to you in connection with this website.
These terms and conditions shall be governed by and construed in accordance with the laws of England without regard to conflicts of law principles. Nothing in these Terms and Conditions will exclude or restrict any duty or liability we may have under applicable rules or regulations.
The content of this website is issued by Asset Value Investors Limited (“AVI”), 2 Cavendish Square, London W1G 0PU.
AVI is authorised and regulated by the Financial Conduct Authority of the United Kingdom (the “FCA”) and is a registered investment adviser with the Securities and Exchange Commission of the United States. While the Investment Manager is registered with the SEC as an investment adviser, it does not comply with the Advisers Act with regard to its non-U.S. clients.
Intended Audience
The information on this website is provided to you for informational purposes only and should not be regarded as an offer or solicitation of an offer to buy or sell any investments or related services that may be referenced on this website. The information contained on this website is subject to change without notice.
This website is primarily intended for UK residents. It is not intended for distribution to, or use by, any U.S. persons or persons in any other country where such distribution or use would be contrary to local law or regulation.
It is your responsibility to observe all applicable laws and regulations of any relevant jurisdiction.
No Tax or Legal Advice
Nothing on this website constitutes investment, legal, tax or other advice nor should it be relied upon in making an investment decision.
Money Laundering
As a result of money laundering regulations, additional documentation for identification purposes may be required when you make your investment. Full details are contained in the relevant subscription documents.
Investment Decisions
As with all financial or investment matters, you should exercise great care in using the information provided on this website or available through links from this website. You should research the facts, opinions and strategies mentioned in this website before making any financial investment decisions. If you are unsure about the meaning of any information provided, please consult your financial adviser or other professional adviser.
No Warranty; Limitation on Liability
Whilst all reasonable care has been taken in the preparation of this website, AVI cannot guarantee the accuracy or completeness of such information, either expressly or implied. Neither AVI, any of its directors, officers or employees, nor any third party vendor, will be liable or have any responsibility of any kind for any loss or damage that you incur in the event of any failure or interruption of this site, or resulting from the act or omission of any other party involved in making this site or the data contained therein available to you, or from any other cause relating to your access to, inability to access, or use of the site or these materials, whether or not the circumstances giving rise to such cause may have been within the control of AVI, or of any vendor providing software or services support.
All information and content on this website is subject to applicable statutes and regulations, furnished “as is”, without warranty of any kind, express or implied, including but not limited to implied warranties of merchantability, fitness for a particular purpose or non-infringement. We make no warranty as to the operation, functionality or availability of this website, that the website will be error-free or that defects will be corrected.
In no event shall AVI be liable to any indirect, incidental, special or consequential damages arising out of or in connection with the use of this website, the inability to use this site or any products or services obtained or stored in or from this website, whether based on contract, tort, strict liability or otherwise. These limitations also apply to any third-party claims against users.
Intellectual Property
Everything on this website is the valuable intellectual property of Asset Value Investors Limited, or their respective suppliers. We protect our intellectual property rights to the full extent of the law.
Copyright Policy
No permission is granted to copy, distribute, modify, post or frame any text, graphics, video, audio, software code, or user interface design or logos.
Hyperlinks
The existence of hyperlinks should not be construed as an endorsement, approval or verification by AVI of any content available on third party sites. By providing access to other websites, we are not recommending the purchase or sale of products or services provided by the website’s sponsoring organization. We do not review any of these third-party sites. AVI reserves the right to require written consent for, or request the removal of, any links to our website.
AVI disclaims all responsibility for the content of third-party sites
Security
For your protection, we require the use of encryption technologies for certain types of communications conducted through this website. While we provide those technologies and use other reasonable precautions to protect confidential information and provide suitable security, we do not guarantee or warrant that information transmitted through the Internet is secure, or that such transmissions will be free from delay, interruption, interception or error.
You acknowledge and agree that users of this website and users, owners, or managers of third party websites may not: (i) collect or store personal data about other users of this website or (ii) upload, e-mail or otherwise transmit any material that contains viruses or any other computer code, files or programs that might interrupt, limit or interfere with the functionality of any computer software, hardware, database or file, or communications equipment that is owned, leased or used by AVI.
Privacy Policy
We encourage you to read AVI’s Privacy Policy which can be obtained by clicking the Privacy Policy button found on the Homepage.
General Terms
Deliberate misuse of any element of this website including, without limitation, hacking, introduction of viruses or similar code, disruption or excessive use or any use in contravention of applicable law, is expressly prohibited and we reserve the right to terminate your access to the website, and at our discretion, pass information to the legal authorities.
We reserve the right at any time on giving notice to change or modify these terms and conditions or to impose new conditions in respect of this website or to change or discontinue any aspect or feature of this website. We shall be entitled to terminate your access to this website at any time on giving notice to you and in any event if you commit any breach of these terms and conditions. We shall have no liability to you for such termination. Notices may be served by any reasonable method including posting on this website.
You shall indemnify us from and against all actions, claims, proceedings, costs and damages (including any damages or compensation paid by us on the advice of its legal advisors to compromise or settle any claim) and all legal costs or expenses arising out of your use of this website, any breach of any applicable law, statute, ordinance, regulation or third party rights and any breach by you of the software licenses and service agreements governing the software made available to you in connection with this website.
These terms and conditions shall be governed by and construed in accordance with the laws of England without regard to conflicts of law principles. Nothing in these Terms and Conditions will exclude or restrict any duty or liability we may have under applicable rules or regulations.
INVESTOR – Risk Warnings
It is very important that you read this warning and disclaimer before proceeding, as it explains certain legal and regulatory restrictions applicable to any investment services and products we provide.
The content of this website is issued by Asset Value Investors Ltd (“AVI”), 2 Cavendish Square, London W1G 0PU
AVI is authorised and regulated by the Financial Conduct Authority (“FCA”) in the United Kingdom.
This website is not directed at any person in any jurisdiction where it is illegal or unlawful to access and use such information. AVI disclaims all responsibility if you access any information in breach of any local law or regulation. All persons who access this website are required to inform themselves and to abide with all applicable local law, regulations and restrictions.
The information on this website is not directed at any person or entity in the United States, and this site is not intended for distribution or to be used by any person or entity in the United States unless those persons or entities are existing investors in funds managed by AVI and they have applicable US exemptions.
Nothing on this website constitutes investment, legal, tax or other advice nor should it be relied upon in making an investment decision.
The funds referred to in this website include: alternative investment funds (“AIFs”), UCITS funds, and a collective investment scheme registered in the Cayman Islands. The promotion of such funds and the distribution of offering materials in relation to such funds is accordingly restricted by law.
Shares in the funds mentioned in this website are not dealt in or on a recognised or designated investment exchange, nor is there a market maker in such shares, and it may therefore be difficult for an investor to dispose of his shares.
The information on this website is neither an offer to sell nor a solicitation of any offer to buy shares in any fund managed by AVI.
An application for shares in any of the funds referred to on this site should only be made having fully read the relevant prospectus and most recent financial statement and semi-annual financial statements published thereafter.
The Information is provided for information purposes only and on the basis that you make your own investment decisions and do not rely upon it.
AVI is not soliciting any action based on it and it does not constitute a personal recommendation or investment advice.
Should you have any queries about the investment funds referred to on this website, you should contact your financial adviser.
Past performance is not an indication of future performance. The value of investments and the income from them may go down as well as up and investors may not get back the amount invested.
The funds noted in this website may be subject to higher risk and volatility than other funds and may not be suitable for all investors.
Exchange rates may cause the value of overseas investments and the income arising from them to rise or fall.
The levels and bases of and reliefs from taxation may change. Any tax reliefs referred to are those currently available and their value depends on the circumstances of the individual investor. Investors should consult their own tax adviser in order to understand any applicable tax consequences.
The information on this website, including any expression of opinion or forecast, has been obtained from, or is based on, sources believed by AVI to be reliable, but are not guaranteed as to their accuracy or completeness and should not be relied upon.
You should be aware that the Internet is not a completely reliable transmission medium. AVI does not accept any liability for any data transmission errors such as data loss or damage or alteration of any kind, including, but not limited to any direct, indirect or consequential damage, arising out of the use of the products or services referred to herein. This does not exclude or restrict any duty or liability that AVI has to its customers under the regulatory system in the United Kingdom.
To make a complaint about this website please send a written complaint for the attention of the Compliance Officer at the registered address: 2 Cavendish Square, London W1G 0PU.
You agree to indemnify, defend, and hold harmless AVI, its affiliates and licensors, and the officers, partners, employees, and agents of AVI and its affiliates and licensors, from and against any and all claims, liabilities, damages, losses, or expenses, including legal fees and costs, arising out of or in any way connected with your access to or use of this website and the Information.
The existence of hyperlinks should not be construed as an endorsement, approval or verification by AVI of any content available on third party websites. By providing access to other websites, we are not recommending the purchase or sale of products or services provided by the website’s sponsoring organization. We do not review any of these third-party websites.
No permission is granted to copy, distribute, modify, post or frame any text, graphics, video, audio, software code, or user interface design or logos.
Nothing on this site should be considered as granting any licence or right under any trademark of AVI or any third party.
Deliberate misuse of any element of this website including, without limitation, hacking, introduction of viruses or similar code, disruption or excessive use or any use in contravention of applicable law, is expressly prohibited and we reserve the right to terminate your access to the website, and at our discretion, pass information to the legal authorities.
We reserve the right at any time on giving notice to change or modify these terms and conditions or to impose new conditions in respect of this website or to change or discontinue any aspect or feature of this website. We shall be entitled to terminate your access to this website at any time on giving notice to you and in any event if you commit any breach of these terms and conditions. We shall have no liability to you for such termination. Notices may be served by any reasonable method including posting on this website.
These terms and conditions shall be governed by and construed in accordance with the laws of England without regard to conflicts of law principles. Nothing in these Terms and Conditions will exclude or restrict any duty or liability we may have under applicable rules or regulations. You irrevocably waive any right to a jury trial in any dispute or proceeding arising from the use of this site.
